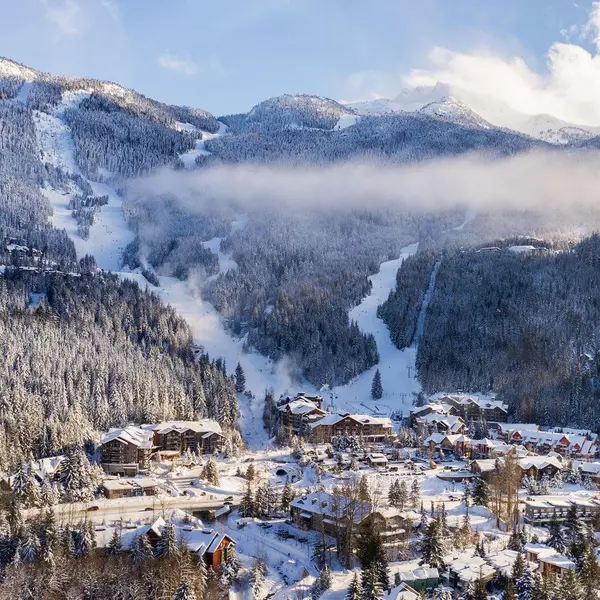
The Ultimate Guide for First-Time Home Buyers in Squamish, BC
A local's guide to buying your first home—with zero judgment, total support, and just the right amount of mountain magic.
First-Time Home Buyer Guide to Squamish, BC
Updated November 2026
Buying your first home in Squamish is exciting, but it comes with plenty of questions. How much should you save? Which neighbourhood suits your lifestyle? What happens between making an offer and getting the keys?
You don’t need to have every answer before you begin. You need a clear plan, a realistic budget and professionals who can help you make informed decisions.
I’m Patricia Jones, a REALTOR® with eXp Realty, serving Squamish and the Sea to Sky Corridor. As an eXp Luxury agent, I bring attentive, thoughtful service to buyers at every price point. Whether you’re considering your first condo, a townhouse or a detached home, my role is to help you understand your options and move forward at a pace that feels comfortable.
This guide covers the practical steps, costs and local considerations involved in buying your first home in Squamish.
Is Squamish a Good Place to Buy Your First Home?
Squamish offers a distinctive combination of mountain access, coastal scenery and everyday amenities. For many buyers, the appeal is having trails, climbing, biking and paddling close to home while remaining connected to Vancouver and Whistler.
Whether it is the right place for your first purchase depends on more than the lifestyle.
Consider your work arrangements, monthly housing budget, transportation needs and how long you expect to own the property. A home should support your daily life as well as your financial priorities.
Think Through the Commute
If you work in Metro Vancouver, test the commute during the hours you would actually travel.
Your journey will depend on where you live in Squamish, your destination, bridge congestion, weather and conditions on Highway 99. Highway incidents can also cause significant delays.
A hybrid schedule may make the drive manageable for some buyers. Others may prefer to work locally or remotely. Include fuel, vehicle maintenance, parking and your time when comparing locations.
Compare Similar Homes and Total Costs
Squamish may offer a different mix of space, housing types and lifestyle benefits than the Vancouver neighbourhoods you are considering. However, it is not automatically the less expensive choice for every property type.
Compare similar homes and include strata fees, property taxes, insurance, utilities and transportation costs.
Buy With a Long-Term Plan
Property values can rise or fall. Buying and selling also involve costs.
Rather than relying on future appreciation, consider whether you can comfortably afford the home and whether it is likely to meet your needs for several years.
Step 1: Establish a Comfortable Home-Buying Budget
Before you spend too much time browsing Squamish homes for sale, speak with a mortgage professional.
A mortgage pre-approval can help establish a potential borrowing range, but it is conditional. The lender must still approve the property and confirm that you meet its requirements.
Your maximum borrowing amount may also be higher than the amount you feel comfortable spending.
Build a budget that leaves room for:
-
Mortgage payments
-
Property taxes
-
Strata fees, where applicable
-
Home insurance
-
Utilities and internet
-
Maintenance and repairs
-
Transportation and other regular expenses
-
Emergency savings
How Much Down Payment Do You Need?
For eligible purchases under $1.5 million, minimum down payments generally start at:
-
5% of the first $500,000
-
10% of the portion above $500,000
Homes priced at $1.5 million or more generally require at least 20% down. Your lender may require more depending on your circumstances and the property.
For example, the minimum down payment on an eligible $800,000 purchase would generally be $55,000: $25,000 on the first $500,000 plus $30,000 on the remaining $300,000.
A down payment below 20% typically requires mortgage default insurance. This protects the lender and adds to your borrowing cost.
Eligible first-time buyers may also have access to a 30-year insured mortgage amortization. A longer amortization can reduce monthly payments, but it generally means paying more interest over time.
Your mortgage professional can compare the options using your actual numbers.
Buying When You’re Self-Employed
If you own a business, work on contract or receive salary and dividends, start the mortgage conversation early.
Different lenders assess self-employed income differently. A broker can explain which documents are needed and how your business structure may affect qualification.
Before changing how you pay yourself for mortgage purposes, coordinate with your accountant and mortgage professional.
Step 2: Budget for Closing Costs and Ongoing Ownership
Your down payment is only one part of the cash you will need.
Costs Associated With Completing the Purchase
Depending on the property and your eligibility for exemptions, these may include:
-
BC Property Transfer Tax
-
GST on applicable new or substantially renovated homes
-
Legal or notary fees and disbursements
-
Inspection and appraisal fees
-
Title insurance, where applicable
-
Adjustments for prepaid property taxes, strata fees or other expenses
-
Moving costs and insurance arrangements
A single percentage estimate will not suit every purchase. A qualifying resale condo and a new townhouse with GST can have very different closing costs.
Ask for a property-specific estimate before committing.
Understand the Deposit
The deposit is paid according to the terms of your purchase contract. It forms part of your purchase funds rather than being an additional charge on top of the price.
It is different from the total down payment. You will need access to deposit funds by the contractual deadline, which may be well before completion.
Plan Beyond Moving Day
Keep a financial cushion for repairs, replacements and unexpected expenses.
For strata properties, budget for monthly fees and the possibility of special levies. A lower strata fee does not automatically mean lower ownership costs over time.
Step 3: Explore First-Time Home Buyer Programs
Several programs may help eligible buyers. Each has its own definition of a first-time buyer, property requirements and timing rules.
Qualifying for one does not automatically qualify you for another.
BC First Time Home Buyers’ Program
This provincial program reduces Property Transfer Tax for eligible purchases.
For a property transfer that fully qualifies:
-
At $500,000 or less, the exemption can cover the full Property Transfer Tax.
-
Above $500,000 and up to $835,000, the exemption amount is $8,000.
-
Above $835,000 and below $860,000, the exemption is gradually reduced.
-
At $860,000 or more, this exemption is unavailable.
For example, an otherwise fully qualifying $800,000 purchase would normally have $14,000 in Property Transfer Tax. An $8,000 exemption would reduce the amount payable to $6,000.
The $835,000 threshold does not mean every qualifying purchase below that amount is completely tax-free.
Other requirements include buyer eligibility, BC residency history, previous principal-residence ownership, property size and occupancy. Your lawyer or notary should confirm your entitlement.
Home Buyers’ Plan: RRSP Withdrawals
The federal Home Buyers’ Plan allows eligible individuals to withdraw up to $60,000 from their RRSPs for a qualifying purchase.
Two eligible buyers could potentially access $120,000 combined.
Withdrawals generally need to be repaid over 15 years. The repayment start date depends on the applicable rules for your withdrawal year. Missed required repayments can become taxable income.
Eligibility includes specific rules about previous principal-residence occupancy and ownership, including a spouse or common-law partner’s ownership in some circumstances. Recent RRSP contributions also require careful timing.
First Home Savings Account
The First Home Savings Account, or FHSA, combines tax-deductible contributions with tax-free qualifying withdrawals.
Key features include:
-
$8,000 in participation room in the year you open your first FHSA
-
A $40,000 lifetime contribution limit
-
Limited carryforward of unused participation room
-
Tax-free qualifying withdrawals, including investment growth
Contribution room begins when you open the account. It does not accumulate for earlier years when you did not have an FHSA.
Eligible buyers can use an FHSA and the Home Buyers’ Plan for the same qualifying purchase.
BC Newly Built Home Exemption
This separate provincial program may reduce or eliminate Property Transfer Tax on a qualifying newly built home.
A full exemption may be available for qualifying homes with a fair market value up to $1.1 million. A partial exemption may apply above $1.1 million and below $1.15 million.
You do not necessarily need to be a first-time buyer, but other eligibility, property and occupancy requirements apply.
Federal First-Time Home Buyers’ GST/HST Rebate
Eligible first-time buyers purchasing a qualifying new home may receive relief of up to $50,000 of federal GST.
For qualifying homes:
-
Up to $1 million, relief can cover 100% of the GST, subject to the maximum rebate.
-
Between $1 million and $1.5 million, the maximum rebate is gradually reduced.
-
At $1.5 million or more, this first-time buyer rebate is unavailable.
Contract dates, construction timelines, occupancy and buyer eligibility matter. Do not assume that every new home or presale qualifies.
Ask whether the advertised price includes GST and whether any rebate has already been credited in the price. Your lawyer and tax advisor can confirm the treatment.
A Program You May Have Heard About That Has Ended
The federal First-Time Home Buyer Incentive, which offered shared-equity assistance, stopped accepting new applications in March 2024.
It should not be included in your current financing plan.
Step 4: Choose Your Priorities and Squamish Neighbourhoods
Start with three to five must-haves. Keep a separate list of preferences you could compromise on.
Useful questions include:
-
How many bedrooms do you need?
-
Do you need a home office?
-
How much parking and equipment storage is essential?
-
Would you prefer walkability or more indoor and outdoor space?
-
Are stairs, yard work or renovation projects practical for you?
-
Could the home accommodate likely changes over the next several years?
Squamish neighbourhoods offer different combinations of housing, terrain and access. Individual streets and buildings can vary considerably.
| Neighbourhood | What buyers should consider |
|---|---|
| Downtown Squamish | Condo and townhouse options, proximity to shops and waterfront areas, parking, construction activity and property-specific flood considerations. |
| Dentville | A mix of older homes and newer infill, central access, neighbouring land uses and potential redevelopment. |
| Northyards | Townhouses and other residential options, trail access, nearby employment uses and possible noise or traffic. |
| Valleycliffe | A mix of housing ages and types, access to trails and hospital services, building condition and property-specific hazards. |
| Garibaldi Estates and Tantalus | Shopping access and varied housing options, with attention to traffic, parking and nearby development. |
| Garibaldi Highlands | Established streets, varied elevations, trails and detached housing, with consideration for maintenance, slopes and winter access. |
| Brackendale | Established residential areas and varied lot sizes, with property-specific checks for flood exposure, drainage and services. |
| Brennan Centre | Newer housing options and proximity to recreation facilities, with attention to strata costs, construction quality and surrounding development. |
| University Heights | Modern homes and hillside settings, with consideration for terrain, transportation and current uses of nearby campus lands. |
| Crumpit Woods | Modern detached homes and trail access, with attention to slopes, maintenance and the overall purchase budget. |
| Hospital Hill | Established homes and varied terrain, where access, parking and building condition deserve close review. |
| Cheekye area | Property-specific review of land use, services, access, flood and debris-flow considerations, and development restrictions. |
Before choosing an area, visit at different times of day and test the routes that matter to you. Check school catchments, childcare availability and transit options directly with the relevant providers.
Step 5: Evaluate Homes Beyond Their Appearance
During showings, look beyond furniture, paint colours and staging.
Consider:
-
Natural light, layout and privacy
-
Traffic and neighbouring noise
-
Parking, visitor parking and storage
-
Heating, ventilation and signs of moisture
-
Windows, roofing and exterior condition
-
Accessibility and future maintenance
-
Renovations that may require permit verification
A renovated kitchen is appealing, but building condition and ownership costs deserve equal attention.
Step 6: Understand Squamish-Specific Due Diligence
Squamish’s coastal and mountain setting makes property-specific research especially valuable.
Depending on the home, this may include reviewing:
-
Flood, debris-flow and slope hazards
-
Insurance availability, coverage and deductibles
-
Title charges, easements and covenants
-
Zoning and permitted uses
-
Building permits and renovation records
-
Suite legality and lender treatment of rental income
-
Nearby development applications
An undeveloped lot or wooded outlook is not a guarantee that the surrounding land will remain unchanged.
I can help identify questions and obtain available information, while inspectors, municipal staff, insurers, lawyers and other specialists provide advice within their areas of expertise.
Buying a Condo or Townhouse
Strata ownership means sharing responsibility for common property and building expenses.
Before proceeding, review relevant documents such as:
-
The Form B Information Certificate
-
Financial statements and budgets
-
Council and general meeting minutes
-
Depreciation reports
-
Contingency reserve funding
-
Existing or proposed special levies
-
Insurance coverage and deductibles
-
Bylaws affecting pets, parking, use and renovations
-
Litigation and significant maintenance issues
The goal is to understand both the home and the financial health of the strata corporation.
Step 7: Make an Informed Offer
A strong offer balances price, terms, timing and protection.
We will review recent comparable sales, the property’s condition and current competition before deciding on a strategy.
Depending on the circumstances, subjects may address financing, inspection, insurance, strata documents or other necessary checks.
Understand BC’s Home Buyer Rescission Period
Many residential purchases in BC have a statutory three-business-day rescission period after offer acceptance.
Where it applies, a buyer who exercises this right generally owes the seller 0.25% of the purchase price. Exceptions and notice requirements apply.
This period does not replace properly considered financing, inspection or other subjects. Presale purchases have a separate legal framework.
Step 8: Complete Due Diligence and Confirm Financing
Once an offer is accepted, work begins on the requirements and deadlines in the contract.
This may include a professional inspection, document review, insurance confirmation and the lender’s property-specific assessment.
Financing approval and any required appraisal should be addressed before removing the financing subject.
A pre-approval alone is not confirmation that the lender will finance a particular property.
Avoid taking on new debt or making major employment or financial changes without discussing them with your mortgage professional.
Step 9: Prepare for Completion and Possession
Your lawyer or notary handles the legal work, confirms the funds required and arranges the transfer of title and purchase funds on completion.
Completion and possession are different events and may occur on different dates.
Before completion, arrange your insurance, provide funds as instructed and confirm moving arrangements. Follow your legal professional’s deadlines rather than leaving preparations until the last day.
On possession day, access is provided according to the contract. We will coordinate the key handover and any agreed arrangements.
Ready to Plan Your First Home Purchase in Squamish?
You do not need to know exactly what you want or be ready to make an offer.
A short discovery call is a practical place to start. We can discuss your preferred property type, comfortable budget and buying timeline, then identify the next steps.
Whether you are preparing for a purchase soon or planning further ahead, I will help you approach the process with clear information and thoughtful local guidance.
Patricia Jones
Personal Real Estate Corporation
EXP Luxury
604-905-8930
homes@patriciajones.ca
https://patriciajones.ca
Instagram: @itspatriciajones
Program information reflects guidance available in November 2026 and may change. Eligibility, financing and tax treatment depend on your circumstances and the property. Confirm the details with your mortgage professional, lawyer or notary, and tax advisor before relying on a benefit.
Recent Posts